Vietnam just earned a new global credential: a fresh branded residences ranking places the country third worldwide, trailing only the UAE and the United States, two markets many times its size. For investors weighing Ho Chi Minh City’s premium towers, that new benchmark changes how the opportunity should be read.
Contents
A new global tally from branded residences ranking research firm Global Branded Residences counts 16,135 branded units across 68 projects nationwide, enough to place Vietnam third worldwide behind the UAE’s 84,972 units and the United States’ 71,592. That position arrives only months after an earlier Savills study had Vietnam sitting fourth globally by project count, a reminder that this market keeps climbing on more than one measure at once.
Ho Chi Minh City carries the largest single share of that count at 3,503 units, ahead of coastal hubs Ha Long and Da Nang. Nineteen of the 68 projects are already complete, while 49 more sit in the pipeline, the sixth largest such pipeline worldwide. Accor alone operates 23 of those projects, close to half the national total, through brands including Sofitel, Fairmont, Mercure and Novotel. “A market this concentrated by brand still has room for genuine diversification.” Marriott and Ritz-Carlton round out the current roster inside the city’s core districts.
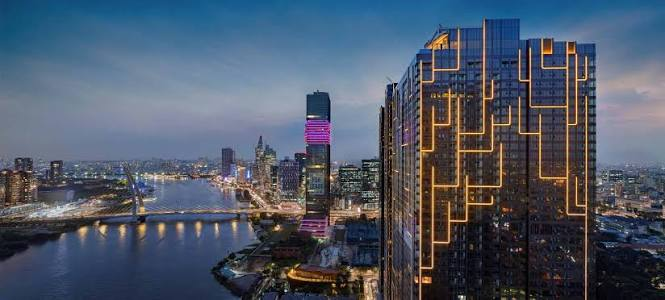
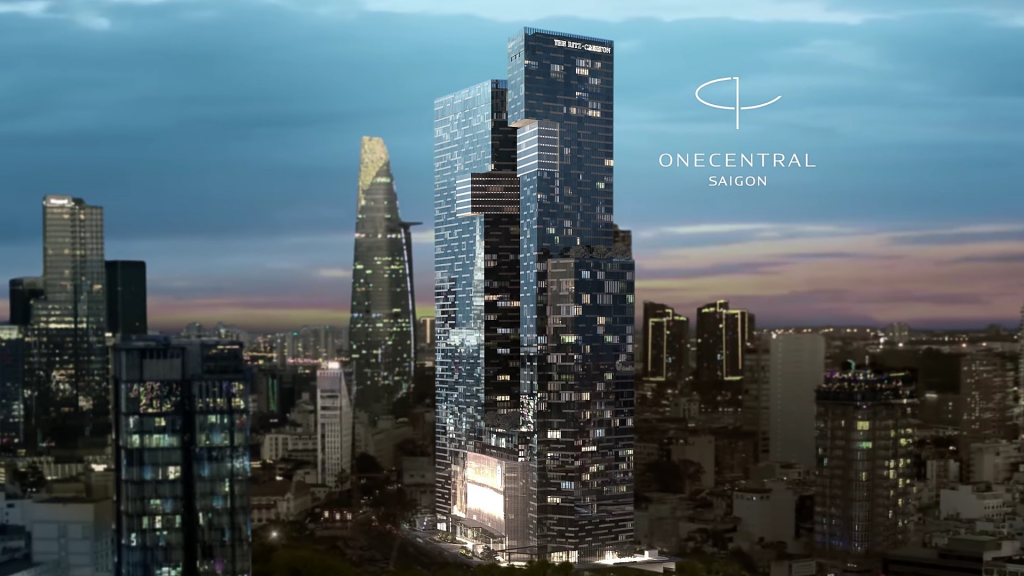
Inside Ho Chi Minh City, the clearest marker of where this new ranking meets real pricing sits at One Central Saigon, where Ritz-Carlton Residences are now trading near VND 1 billion per square meter, equivalent to roughly USD 40,000. That figure matters less as a single transaction price and more as a ceiling reference for every other branded project competing for the same buyer pool in District 1 and its immediate surroundings.
With only 3,503 branded units across the entire city, against Ha Long’s 2,860 and Da Nang’s 1,429, HCMC’s inner core remains the scarcest branded inventory in the country relative to demand. A global podium finish gives that scarcity outside validation, rather than a story told only by local brokers. “Scarce supply with a verified global ranking behind it prices differently from scarce supply alone.” For owners already holding units nearby, that reference point supports how resale value gets argued going forward.
Vietnam’s 49 pipeline projects, the sixth largest reserve of unbuilt branded supply worldwide, carry more weight for long term positioning than the 16,135 units already standing. Savills’ own research on the Asia Pacific pipeline points to supply growth of 152 percent by 2032, the fastest pace in the region, with the country already ahead of Thailand, India and China on project count heading into that period.
Coastal resort hubs such as Da Nang, Phu Quoc and Hoi An hold most of today’s completed inventory. But the brands entering next, beyond Accor’s current lead, are expected to concentrate more heavily inside urban cores like Ho Chi Minh City rather than beach resorts. That shift favors investors already positioned in the city’s core submarket, ahead of the broader diversification still to come. “Today’s ranking is a snapshot of a market still building toward its real ceiling.” Each new project added to the pipeline becomes another data point worth tracking before the next global tally is published.
Vietnam’s climb to third worldwide adds a credential that few emerging luxury markets can claim, and it is one more reason core HCMC inventory keeps outperforming expectations set years ago. Readers tracking how this shift fits into a broader ownership mindset can revisit our earlier look at the city’s move toward a buy to operate approach to luxury apartments. Investors evaluating a specific branded project inside the core districts can also browse current listings in the same submarket.
Looking for trustworthy real estate agent? La Quinta is your one-stop partner. We offer turnkey support for buying/selling, renting, interiror design & furrnishing, and fully property management. Contact us today.
Mr. KIM DONNIE (Korean & English)
Associate Director
Phone number: 08 98 48 38 68
Email: kdh@lqltd.com
Zalo: 08 98 48 38 68 (La Quinta)
Kakaotalk ID : kdhrpm
WeChat: LQ-kdh
Whatsapp: +84 89 848 38 68
Ms. TRẦN HOÀNG OANH (Vietnamese & English)
Director of Residential and Investment Team
Phone number: (+84) 937 836 896
Email: christine@lqltd.com
Zalo: 09 3783 6896 (Oanh – Christine)
Whatsapp: +84 937 83 896
Wechat: Oanhhoangtran